highOrderPortfolios
Design of High-Order Portfolios Including Skewness and Kurtosis
The classical Markowitz's mean-variance portfolio formulation ignores
heavy tails and skewness. High-order portfolios use higher order moments to
better characterize the return distribution. Different formulations and fast
algorithms are proposed for high-order portfolios based on the mean, variance,
skewness, and kurtosis.
The package is based on the papers:
R. Zhou and D. P. Palomar (2021). "Solving High-Order Portfolios via
Successive Convex Approximation Algorithms."
highOrderPortfolios
The classical Markowitz's mean-variance portfolio formulation ignores heavy tails and skewness. High-order portfolios use higher order moments to better characterize the return distribution. Different formulations and fast algorithms are proposed for high-order portfolios based on the mean, variance, skewness, and kurtosis. The package is based on the papers Zhou and Palomar (2021) and Wang, Zhou, Ying, and Palomar (2022).
Installation
The package can be installed from CRAN or GitHub:
# install stable version from CRAN
install.packages("highOrderPortfolios")

# install development version from GitHub
devtools::install_github("dppalomar/highOrderPortfolios")
To get help:
library(highOrderPortfolios)
help(package = "highOrderPortfolios")
?design_MVSK_portfolio_via_sample_moments
?design_MVSK_portfolio_via_skew_t
To cite highOrderPortfolios in publications:
citation("highOrderPortfolios")
Usage
library(highOrderPortfolios)
data(X50)

# non-parametric case: estimate sample moments
X_moments <- estimate_sample_moments(X50)

# parametric case: estimate the multivariate skew t distribution
X_skew_t_params <- estimate_skew_t(X50)

# choose hyper-parameter moment weights for the MVSK formulation
xi <- 10
lmd <- c(1, xi/2, xi*(xi+1)/6, xi*(xi+1)*(xi+2)/24)

# design portfolio
sol_nonparam <- design_MVSK_portfolio_via_sample_moments(lmd, X_moments)
sol_param    <- design_MVSK_portfolio_via_skew_t(lmd, X_skew_t_params)

# plot
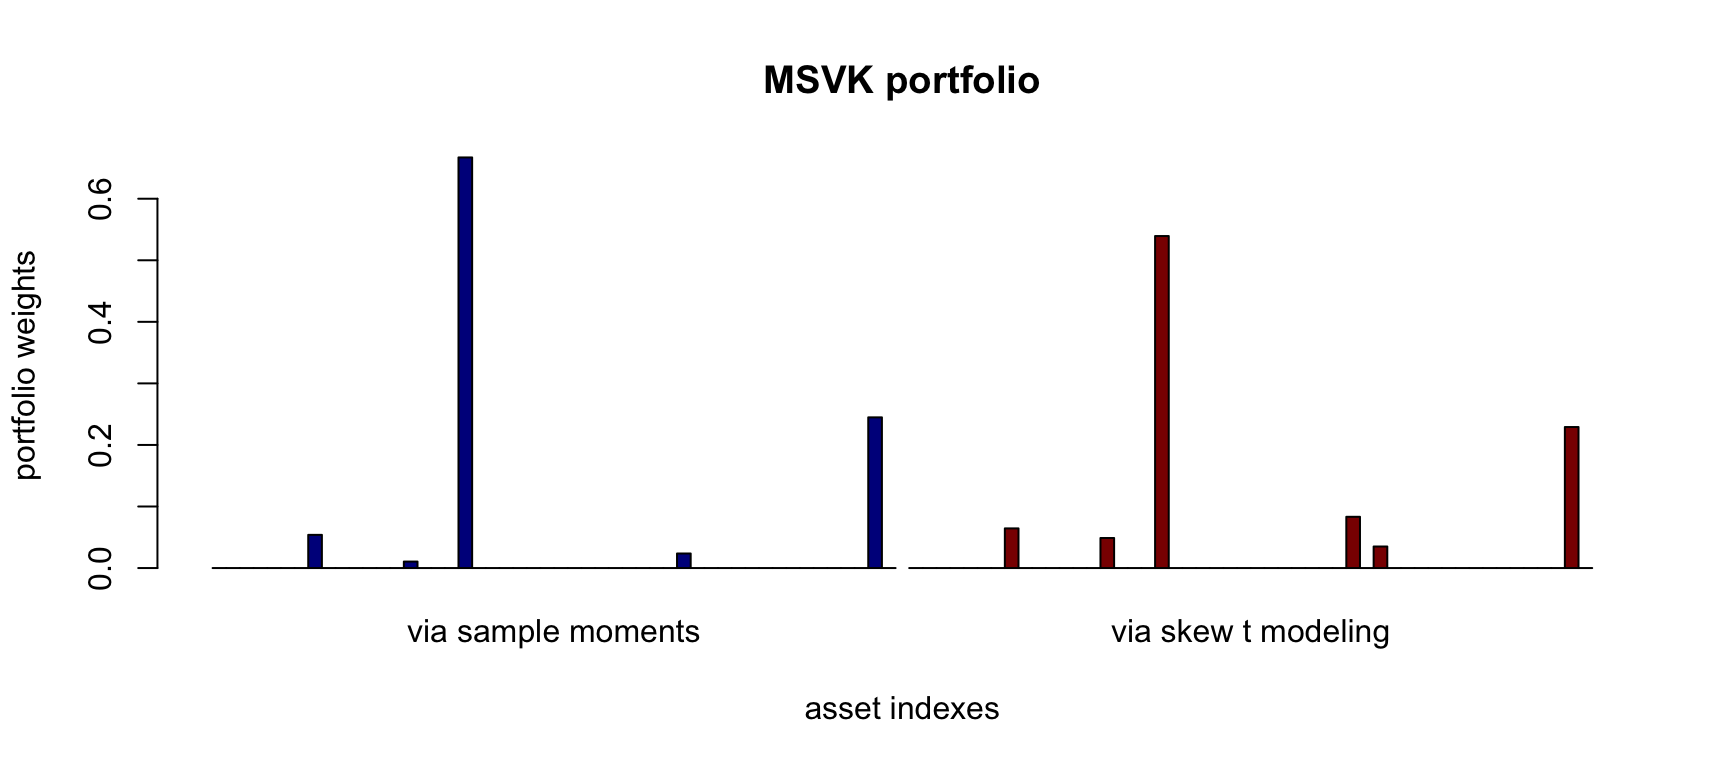
barplot(cbind("via sample moments" = sol_nonparam$w, "via skew t modeling" = sol_param$w), beside = TRUE,
        col = c(rep("darkblue", 50), rep("darkred", 50)),
        main = "MSVK portfolio", xlab = "asset indexes", ylab = "portfolio weights")
Documentation
For more detailed information, please check the vignette: CRAN-vignette and GitHub-vignette.
Links
README file: CRAN-readme and GitHub-readme.
Vignette: CRAN-vignette and GitHub-vignette.