TemporalHazard
Temporal Parametric Hazard Modeling
Provides native R implementations of the multiphase parametric
hazard model of Blackstone, Naftel, and Turner (1986)
TemporalHazard


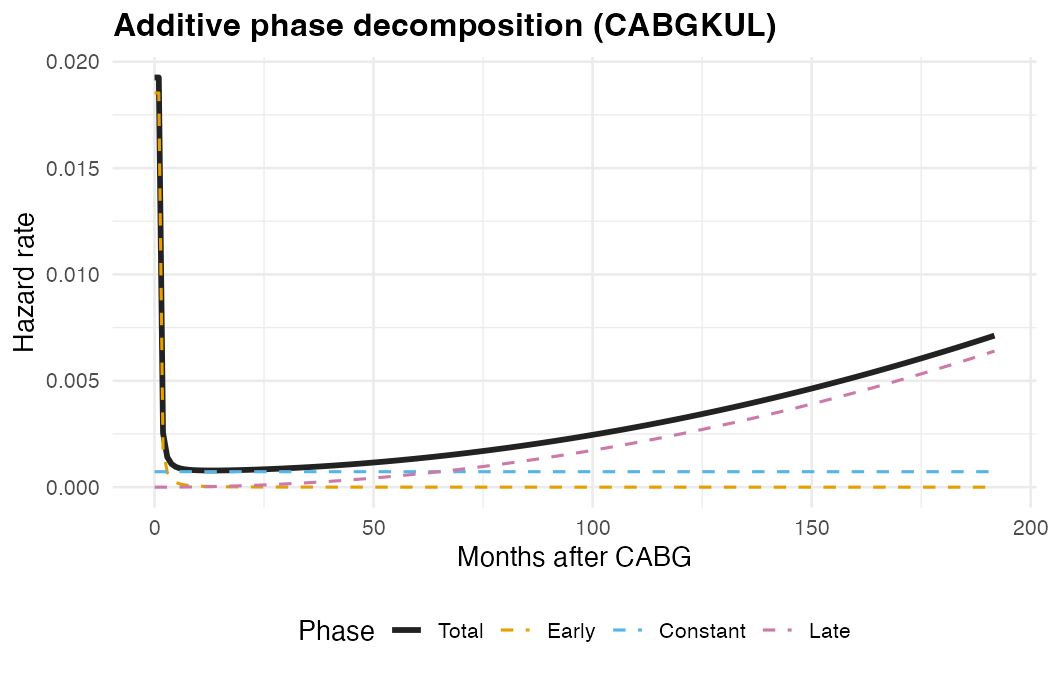
TemporalHazard is a pure-R implementation of the multiphase parametric hazard model of Blackstone, Naftel, and Turner (1986). It decomposes the overall hazard of an event into additive temporal phases (early, constant, and late), each governed by the generalized temporal decomposition family. This structure captures real clinical risk patterns that standard single-distribution models (Weibull, log-normal) cannot represent.
Provenance and maintenance
The original SAS/C HAZARD code was developed at the University of Alabama at Birmingham (UAB). The SAS/C code and this R package are currently developed and maintained at The Cleveland Clinic Foundation. The R code in TemporalHazard was wholly developed at The Cleveland Clinic Foundation.
Why multiphase?
After cardiac surgery, the risk of death is not constant. It starts high in the immediate post-operative period (early phase), settles to a low background rate (constant phase), and eventually rises again as patients age (late phase). A single Weibull curve forces a monotone shape; a multiphase model captures all three regimes simultaneously.
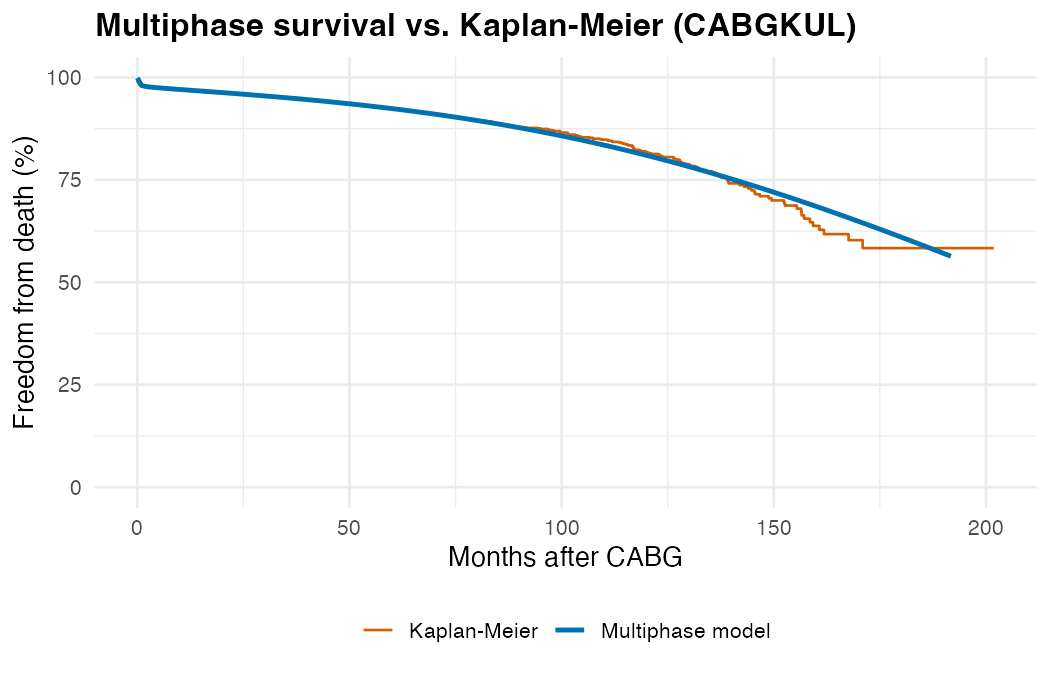
The resulting survival curve closely tracks the nonparametric Kaplan-Meier estimate, and as a smooth parametric curve it supports covariate adjustment, prediction, and extrapolation.
Key capabilities
| Feature | Status |
|---|---|
| Multi-phase hazard modeling (early, constant, late phases) | :white_check_mark: |
| Five parametric distributions (Weibull, exponential, log-logistic, log-normal, multiphase) | :white_check_mark: |
| Right, left, interval, and counting-process censoring | :white_check_mark: |
Repeating events (epoch decomposition via Surv(start, stop, event)) |
:white_check_mark: |
| Time-varying covariates (piecewise windows) | :white_check_mark: |
| Weighted events across all distributions | :white_check_mark: |
| Automatic stepwise covariate selection (forward, backward, stepwise; score (default), Wald or AIC) | :white_check_mark: |
| Conservation of Events theorem for numerically stable parameter estimation | :white_check_mark: |
| Covariance and correlation matrix estimation | :white_check_mark: |
Delta-method confidence limits on predict() (se.fit = TRUE) |
:white_check_mark: |
Seven hzr_* utility functions (Kaplan-Meier, Nelson, GOF, deciles, calibration, bootstrap, competing risks) |
:white_check_mark: |
Per-phase confidence limits (decompose = TRUE, se.fit = TRUE) |
:construction: |
| 4-phase example dataset and vignette | :construction: |
:white_check_mark: = implemented :construction: = planned
Installation
# Install from CRAN
install.packages("TemporalHazard")
# Or install the development version from GitHub
remotes::install_github("ehrlinger/TemporalHazard")
TemporalHazard requires R >= 4.1.0 and imports the
survival package. It does not
attach it, which is why the examples below call survival::Surv().
Optional packages for visualization and vignettes include ggplot2, numDeriv,
and quarto.
Quick start
Single-phase model
library(TemporalHazard)
data(cabgkul)

# Intercept-only Weibull on 5,880 CABG patients
fit <- hazard(
  survival::Surv(int_dead, dead) ~ 1,
  data  = cabgkul,
  dist  = "weibull",
  theta = c(mu = 0.10, nu = 1.0),
  fit   = TRUE
)
summary(fit)
Multiphase model
# Three-phase additive hazard decomposition
fit_mp <- hazard(
  survival::Surv(int_dead, dead) ~ 1,
  data   = cabgkul,
  dist   = "multiphase",
  phases = list(
    early    = hzr_phase("cdf", t_half = 0.2, nu = 1, m = 1,
                          fixed = "shapes"),
    constant = hzr_phase("constant"),
    late     = hzr_phase("g3",  tau = 1, gamma = 3, alpha = 1, eta = 1,
                          fixed = "shapes")
  ),
  fit = TRUE
)
summary(fit_mp)

# Per-phase decomposition of cumulative hazard
t_grid <- seq(0.01, max(cabgkul$int_dead) * 0.9, length.out = 200)
predict(fit_mp, newdata = data.frame(time = t_grid),
        type = "cumulative_hazard", decompose = TRUE)
Each phase is specified with hzr_phase(), which sets the temporal shape
type and starting values. The optimizer estimates both the phase-specific
scale parameters and shape parameters jointly. Covariates are supported via
the formula interface (see vignette("fitting-hazard-models")).
Documentation
- Clinical Analysis Walkthrough: complete end-to-end workflow from Kaplan-Meier baseline through validated multivariable model.
- Getting Started: first fit-predict workflow with visualizations.
- Fitting Hazard Models: intercept-only through multiphase and multi-endpoint models.
- Prediction & Visualization: survival curves, decomposed hazard, patient-specific risk profiles.
- Inference & Diagnostics: bootstrap CIs, decile-of-risk validation, sensitivity analysis.
- Mathematical Foundations: the generalized decomposition, additive hazard model, censoring likelihood, and time-varying covariates.
- Package Architecture: internal design, golden fixtures, and dataset catalog.
- SAS-to-R Migration: statement-by-statement mapping from SAS HAZARD syntax.
Development
install.packages(c("devtools", "roxygen2", "pkgdown", "testthat"))
devtools::install_deps(dependencies = TRUE)
devtools::test()
devtools::check()
GitHub Actions runs multi-platform R CMD check on every push and pull request. Coverage is published to Codecov and the pkgdown site deploys automatically from main.
See the milestones for planned work.