sparsegl
Sparse Group Lasso
Efficient implementation of sparse group lasso with optional
bound constraints on the coefficients; see

sparsegl 
The goal of sparsegl is to fit regularization paths for sparse group-lasso penalized learning problems. The model is typically fit for a sequence of regularization parameters $\lambda$. Such estimators minimize
$$ -\ell(\beta | y,\ \mathbf{X}) + \lambda(1-\alpha)\sum_{g\in G} \lVert\beta_g\rVert_2 + \lambda\alpha \lVert\beta\rVert_1. $$
The main focus of this package is for the case where the loglikelihood
corresponds to Gaussian or logistic regression. But we also provide the
ability to fit arbitrary GLMs using stats::family() objects. Details
may be found in Liang, Cohen, Sólon Heinsfeld, Pestilli, and McDonald
(2024).
Installation
You can install the released version of sparsegl from CRAN with:
install.packages("sparsegl")
You can install the development version from GitHub with:
# install.packages("remotes")
remotes::install_github("dajmcdon/sparsegl")
Minimal Example
set.seed(1010)
n <- 100
p <- 200
X <- matrix(data = rnorm(n * p, mean = 0, sd = 1), nrow = n, ncol = p)
eps <- rnorm(n, mean = 0, sd = 1)
beta_star <- c(
  rep(5, 5), c(5, -5, 2, 0, 0),
  rep(-5, 5), c(2, -3, 8, 0, 0), rep(0, (p - 20))
)
y <- X %*% beta_star + eps
groups <- rep(1:(p / 5), each = 5)
fit1 <- sparsegl(X, y, group = groups)
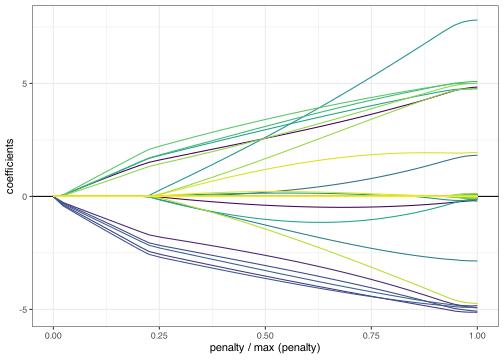
plot(fit1, y_axis = "coef", x_axis = "penalty", add_legend = FALSE)
References
Liang, X., Cohen, A., Sólon Heinsfeld, A., Pestilli, F., and McDonald,
D.J. 2024. “sparsegl: An R Package for Estimating Sparse Group Lasso.”
Journal of Statistical Software 110(6), 1–23.
https://doi.org/10.18637/jss.v110.i06.