dfms
Dynamic Factor Models
Efficient estimation of Dynamic Factor Models using the Expectation Maximization (EM) algorithm
or Two-Step (2S) estimation, supporting datasets with missing data and mixed-frequency nowcasting applications.
Factors follow a stationary VAR process of order p. Estimation options include: running the Kalman Filter and
Smoother once with PCA initial values (2S) as in Doz, Giannone and Reichlin (2011)
dfms 





dfms provides efficient estimation of Dynamic Factor Models in R via the EM Algorithm. Factors are assumed to follow a stationary VAR
process of order p. Estimation can be done in 3 different ways following:
-
Doz, C., Giannone, D., & Reichlin, L. (2011). A two-step estimator for large approximate dynamic factor models based on Kalman filtering. Journal of Econometrics, 164(1), 188-205. doi:10.1016/j.jeconom.2011.02.012
-
Doz, C., Giannone, D., & Reichlin, L. (2012). A quasi-maximum likelihood approach for large, approximate dynamic factor models. Review of Economics and Statistics, 94(4), 1014-1024. doi:10.1162/REST_a_00225
-
Banbura, M., & Modugno, M. (2014). Maximum likelihood estimation of factor models on datasets with arbitrary pattern of missing data. Journal of Applied Econometrics, 29(1), 133-160. doi:10.1002/jae.2306
The default is em.method = "auto", which chooses "BM" following Banbura & Modugno (2014) with missing data or mixed frequency, and "DGR" following Doz, Giannone & Reichlin (2012) otherwise. Using em.method = "none" generates Two-Step estimates following Doz, Giannone & Reichlin (2011). This is extremely efficient on bigger datasets. PCA and Two-Step estimates are also reported in EM-estimation. All methods support missing data, but em.method = "DGR" does not model them in EM iterations.
The package is now at a 1.0.0 release and includes news() for Banbura and Modugno (2014) style news decomposition of forecast updates.
Comparison with Other Packages
dfms provides a simple, numerically robust, and computationally efficient implementation of (linear Gaussian) Dynamic Factor Models for R, allowing straightforward application to time series dimensionality reduction, forecasting, and nowcasting tasks. It is based on efficient C++ code, making dfms orders of magnitude faster than other packages that can be used to fit dynamic factor models such as MARSS, or nowcasting and nowcastDFM geared to mixed-frequency nowcasting applications - which dfms now also supports. For large-scale nowcasting models the DynamicFactorMQ class in the statsmodels Python library is likely the best implementation - see the example by Chad Fulton.
The dfms package is not intended to fit more general forms of the state space model like MARSS.
Installation
# CRAN
install.packages("dfms")

# Development Version
install.packages('dfms', repos = c('https://ropensci.r-universe.dev', 'https://cloud.r-project.org'))
Usage Example
library(dfms)

# Fit DFM with 6 factors and 3 lags in the transition equation
mod <- DFM(diff(BM14_M), r = 6, p = 3)
## Converged after 32 iterations.
# 'dfm' methods
summary(mod)
## Dynamic Factor Model: n = 92, T = 356, r = 6, p = 3, %NA = 25.8366
##
## Call:  DFM(X = diff(BM14_M), r = 6, p = 3)
##
## Summary Statistics of Factors [F]
##       N     Mean   Median      SD       Min      Max
## f1  356  -0.1189   0.4409  4.0228  -22.9164   7.8513
## f2  356  -0.4615  -0.3476  2.9201   -9.0973  10.7003
## f3  356  -0.0173   0.0377  2.2719   -8.5067   7.3009
## f4  356   -0.007  -0.1338  1.9378   -9.5052   9.3673
## f5  356    0.237   0.1091  2.0857   -8.7252   9.6715
## f6  356  -0.8361   -0.304  3.1406  -11.6611  15.4897
##
## Factor Transition Matrix [A]
##       L1.f1    L1.f2     L1.f3    L1.f4    L1.f5    L1.f6    L2.f1    L2.f2    L2.f3
## f1  0.53029 -0.53009  0.367302  0.04607 -0.06351  0.10310  0.02457  0.11673 -0.12638
## f2 -0.28380  0.07421 -0.032292  0.29741 -0.10094  0.21989  0.09958 -0.09149  0.06708
## f3  0.17607  0.12979  0.378798 -0.06662 -0.12236  0.06685 -0.08068  0.09101 -0.22232
## f4  0.02711  0.08936  0.004643  0.37159  0.12100 -0.02763  0.01234 -0.05147  0.02195
## f5 -0.26227 -0.03469 -0.046294  0.12712  0.26847  0.03141  0.06400  0.01971  0.04806
## f6  0.08251  0.17619 -0.013374 -0.08731 -0.03875  0.27812 -0.01662  0.04877  0.02279
##       L2.f4     L2.f5    L2.f6    L3.f1    L3.f2    L3.f3    L3.f4    L3.f5    L3.f6
## f1  0.23135  0.117184  0.21941  0.18478  0.02259 -0.03719 -0.07236 -0.03026 -0.12606
## f2 -0.09768 -0.043057  0.08489  0.21107  0.16261  0.03057  0.04835  0.12249  0.13357
## f3  0.09799 -0.060666 -0.18028 -0.02773  0.01798  0.10143 -0.12420  0.04207 -0.07011
## f4  0.01266  0.050912  0.05144 -0.05601  0.04665  0.05710 -0.11412 -0.05680 -0.01609
## f5 -0.03965 -0.009952 -0.18471  0.08332 -0.04640 -0.02047  0.02458  0.16397  0.07820
## f6  0.01163 -0.100859  0.07152  0.00792  0.06071  0.11381  0.02520 -0.17897  0.30328
##
## Factor Covariance Matrix [cov(F)]
##           f1        f2        f3        f4        f5        f6
## f1  16.1832   -0.4329    0.2483   -0.8224*  -1.7708*   0.7702
## f2  -0.4329    8.5272    0.0051    0.2954   -0.2114    4.2080*
## f3   0.2483    0.0051    5.1614   -0.1851   -0.3979    0.2979
## f4  -0.8224*   0.2954   -0.1851    3.7550    0.4344*   0.2211
## f5  -1.7708*  -0.2114   -0.3979    0.4344*   4.3503   -1.9785*
## f6   0.7702    4.2080*   0.2979    0.2211   -1.9785*   9.8634
##
## Factor Transition Error Covariance Matrix [Q]
##         u1      u2      u3      u4      u5      u6
## u1  7.2142  0.1151 -0.8208 -0.4379  0.4110 -0.1206
## u2  0.1151  4.8724  0.1076 -0.1438  0.1418  0.1759
## u3 -0.8208  0.1076  4.0584 -0.0788  0.0163  0.0038
## u4 -0.4379 -0.1438 -0.0788  3.0003  0.2562  0.0243
## u5  0.4110  0.1418  0.0163  0.2562  2.8410 -0.1031
## u6 -0.1206  0.1759  0.0038  0.0243 -0.1031  2.9284
##
## Summary of Residual AR(1) Serial Correlations
##    N     Mean   Median      SD      Min     Max
##   92  -0.0644  -0.1024  0.2702  -0.5113  0.6674
##
## Summary of Individual R-Squared's
##    N    Mean  Median      SD     Min     Max
##   92  0.4556  0.4069  0.3041  0.0112  0.9989
plot(mod)
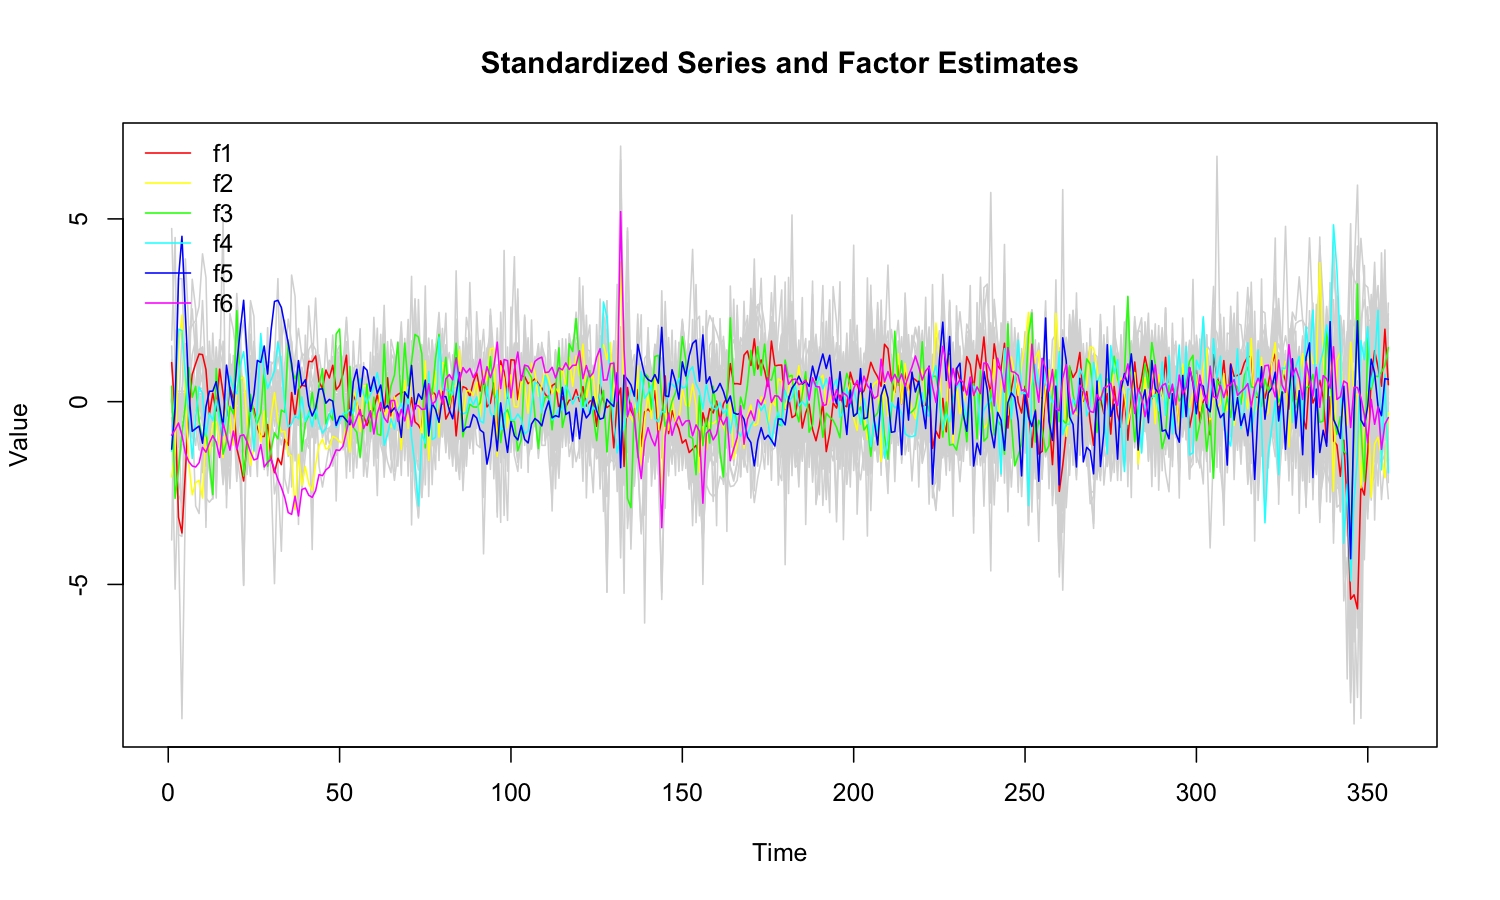
as.data.frame(mod) |> head()
##   Method Factor Time      Value
## 1    PCA     f1    1  0.8445713
## 2    PCA     f1    2  0.5259228
## 3    PCA     f1    3 -1.2107116
## 4    PCA     f1    4 -1.5399532
## 5    PCA     f1    5 -0.4631786
## 6    PCA     f1    6  0.2399304
# Forecasting 12 periods ahead
fc <- predict(mod, h = 12)

# 'dfm_forecast' methods
plot(fc, xlim = c(320, 370))
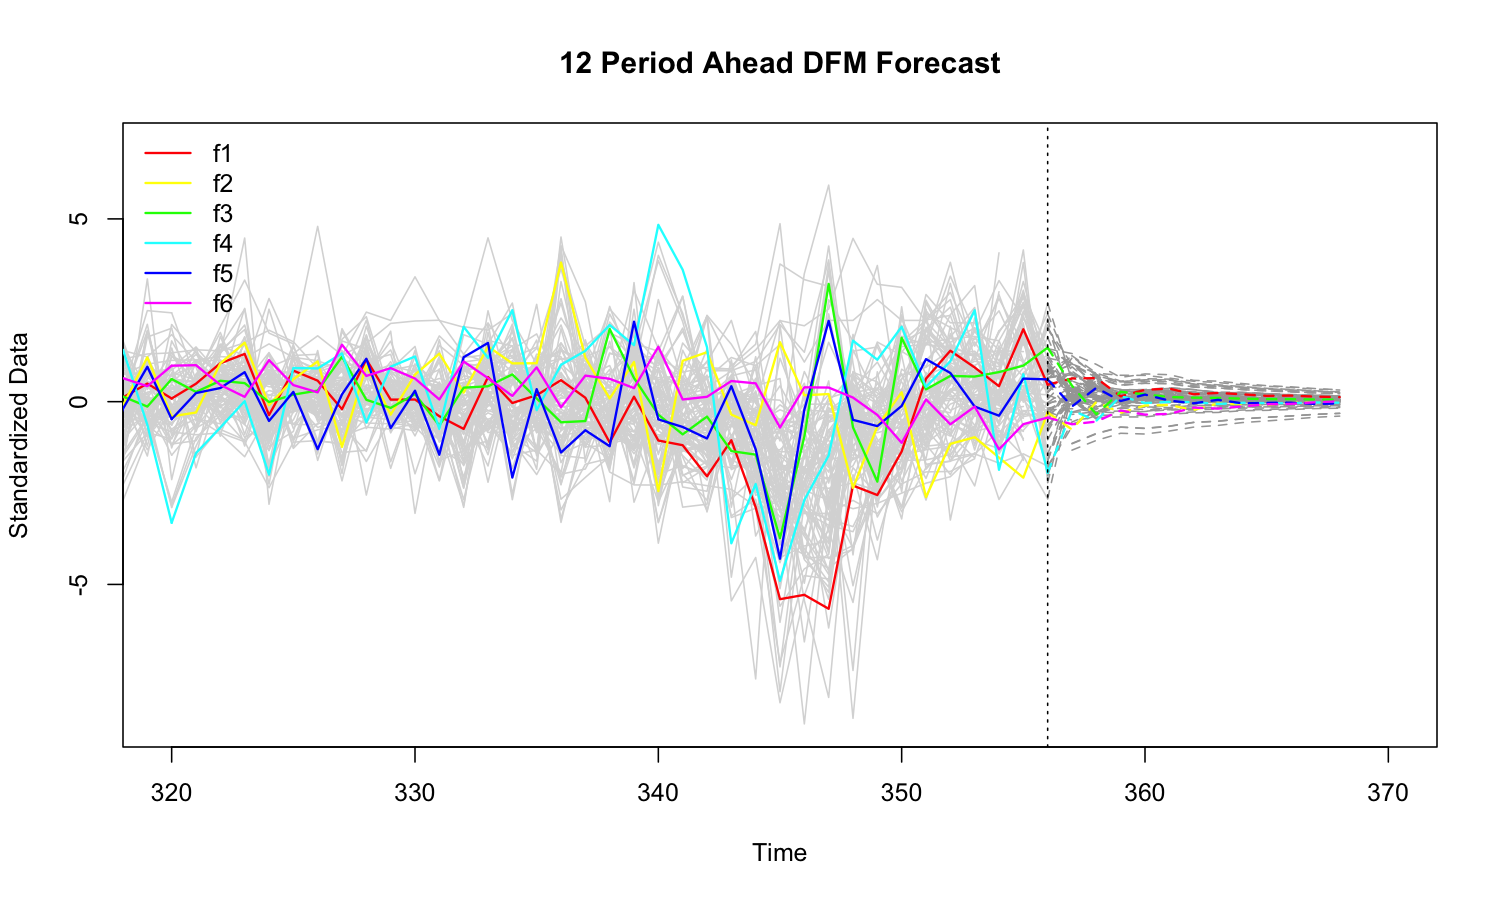
as.data.frame(fc) |> head()
##   Variable Time Forecast      Value
## 1       f1    1    FALSE   4.179331
## 2       f1    2    FALSE  -1.368577
## 3       f1    3    FALSE -12.845157
## 4       f1    4    FALSE -14.562265
## 5       f1    5    FALSE  -7.791254
## 6       f1    6    FALSE  -1.254970