WH
Enhanced Implementation of Whittaker-Henderson Smoothing
An enhanced implementation of Whittaker-Henderson smoothing for the graduation
of one-dimensional and two-dimensional actuarial tables used to quantify Life Insurance risks.
'WH' is based on the methods described in Biessy (2025)
Revisiting Whittaker-Henderson Smoothing

What is Whittaker-Henderson smoothing ?
Origin
Whittaker-Henderson (WH) smoothing is a graduation method designed to mitigate the effects of sampling fluctuations in a vector of evenly spaced discrete observations. Although this method was originally proposed by Bohlmann (1899), it is named after Whittaker (1923), who applied it to graduate mortality tables, and Henderson (1924), who popularized it among actuaries in the United States. The method was later extended to two dimensions by Knorr (1984). WH smoothing may be used to build experience tables for a broad spectrum of life insurance risks, such as mortality, disability, long-term care, lapse, mortgage default and unemployment.
The one-dimensional case
Let $\mathbf{y}$ be a vector of observations and $\mathbf{w}$ a vector of positive weights, both of size $n$. The estimator associated with Whittaker-Henderson smoothing is given by:
$$ \hat{\mathbf{y}} = \underset{\boldsymbol{\theta}}{\text{argmin}}{F(\mathbf{y},\mathbf{w},\boldsymbol{\theta}) + R_{\lambda,q}(\boldsymbol{\theta})} $$
where:
-
$F(\mathbf{y},\mathbf{w},\boldsymbol{\theta}) = \underset{i = 1}{\overset{n}{\sum}} w_i(y_i - \theta_i)^2$ represents a fidelity criterion with respect to the observations,
-
$R_{\lambda,q}(\boldsymbol{\theta}) = \lambda \underset{i = 1}{\overset{n - q}{\sum}} (\Delta^q\boldsymbol{\theta})_i^2$ represents a smoothness criterion.
In the latter expression, $\lambda \ge 0$ is a smoothing parameter and $\Delta^q$ denotes the forward difference operator of order $q$, such that for any $i\in{1,\dots,n - q}$:
$$ (\Delta^q\boldsymbol{\theta})i = \underset{k = 0}{\overset{q}{\sum}} \begin{pmatrix}q \ k\end{pmatrix}(- 1)^{q - k} \theta{i + k}. $$
Define $W = \text{Diag}(\mathbf{w})$, the diagonal matrix of weights, and $D_{n,q}$ as the order $q$ difference matrix of dimensions $(n-q) \times n$, such that $(D_{n,q}\boldsymbol{\theta})_i = (\Delta^q\boldsymbol{\theta})_i$ for all $i \in [1, n-q]$. The first- and second-order difference matrices are given by:
$$ D_{n,1} = \begin{bmatrix} -1 & 1 & 0 & \ldots & 0 \ 0 & -1 & 1 & \ldots & 0 \ \vdots & \vdots & \vdots & \ddots & \vdots \ 0 & \ldots & 0 & -1 & 1 \ \end{bmatrix} \quad\text{and}\quad D_{n,2} = \begin{bmatrix} 1 & -2 & 1 & 0 & \ldots & 0 \ 0 & 1 & -2 & 1 & \ldots & 0 \ \vdots & \vdots & \vdots & \vdots & \ddots & \vdots \ 0 & \ldots & 0 & 1 & -2 & 1 \ \end{bmatrix}. $$
while higher-order difference matrices follow the recursive formula $D_{n,q} = D_{n - 1,q - 1}D_{n,1}$. The fidelity and smoothness criteria can be rewritten with matrix notations as:
$$ F(\mathbf{y},\mathbf{w},\boldsymbol{\theta}) = (\mathbf{y} - \boldsymbol{\theta})^TW(\mathbf{y} - \boldsymbol{\theta}) \quad \text{and} \quad R_{\lambda,q}(\boldsymbol{\theta}) = \lambda\boldsymbol{\theta}^TD_{n,q}^TD_{n,q}\boldsymbol{\theta} $$
and the WH smoothing estimator thus becomes:
$$ \hat{\mathbf{y}} = \underset{\boldsymbol{\theta}}{\text{argmin}} \left\lbrace(\mathbf{y} - \boldsymbol{\theta})^TW(\mathbf{y} - \boldsymbol{\theta}) + \boldsymbol{\theta}^TP_{\lambda}\boldsymbol{\theta}\right\rbrace $$
where $P_{\lambda} = \lambda D_{n,q}^TD_{n,q}$.
The two-dimensional case
In the two-dimensional case, consider a matrix $Y$ of observations and a matrix $\Omega$ of non-negative weights, both of dimensions $n_x \times n_z$. The WH smoothing estimator solves:
$$ \widehat{Y} = \underset{\Theta}{\text{argmin}}{F(Y,\Omega, \Theta) + R_{\lambda,q}(\Theta)} $$
where:
-
$F(Y,\Omega, \Theta) = \sum_{i = 1}^{n_x}\sum_{j = 1}^{n_z} \Omega_{i,j}(Y_{i,j} - \Theta_{i,j})^2$ represents a fidelity criterion with respect to the observations,
-
$R_{\lambda,q}(\Theta) = \lambda_x \sum_{j = 1}^{n_z}\sum_{i = 1}^{n_x - q_x} (\Delta^{q_x}\Theta_{\bullet,j})i^2 + \lambda_z \sum{i = 1}^{n_x}\sum_{j = 1}^{n_z - q_z} (\Delta^{q_z}\Theta_{i,\bullet})_j^2$ is a smoothness criterion with $\lambda = (\lambda_x,\lambda_z)$.
This latter criterion adds row-wise and column regularization criteria to $\Theta$, with respective orders $q_x$ and $q_z$, weighted by non-negative smoothing parameters $\lambda_x$ and $\lambda_z$. In matrix notation, let $\mathbf{y} = \textbf{vec}(Y)$, $\mathbf{w} = \textbf{vec}(\Omega)$, and $\boldsymbol{\theta} = \textbf{vec}(\Theta)$ as the vectors obtained by stacking the columns of the matrices $Y$, $\Omega$, and $\Theta$, respectively. Additionally, denote $W = \text{Diag}(\mathbf{w})$ and $n = n_x \times n_z$. The fidelity and smoothness criteria become:
$$ \begin{aligned} F(\mathbf{y},\mathbf{w}, \boldsymbol{\theta}) &= (\mathbf{y} - \boldsymbol{\theta})^TW(\mathbf{y} - \boldsymbol{\theta}) \ R_{\lambda,q}(\boldsymbol{\theta}) &= \boldsymbol{\theta}^{T}(\lambda_x I_{n_z} \otimes D_{n_x,q_x}^{T}D_{n_x,q_x} + \lambda_z D_{n_z,q_z}^{T}D_{n_z,q_z} \otimes I_{n_x}) \boldsymbol{\theta}. \end{aligned} $$
and the associated estimator takes the same form as in the one-dimensional case except
$$P_{\lambda} = \lambda_x I_{n_z} \otimes D_{n_x,q_x}^{T}D_{n_x,q_x} + \lambda_z D_{n_z,q_z}^{T}D_{n_z,q_z} \otimes I_{n_x}.$$
An explicit solution
If $W + P_{\lambda}$ is invertible, the WH smoothing equation admits the closed-form solution:
$$\hat{\mathbf{y}} = (W + P_{\lambda})^{-1}W\mathbf{y}.$$
Indeed, as a minimum, $\hat{\mathbf{y}}$ satisfies:
$$0 = \left.\frac{\partial}{\partial \boldsymbol{\theta}}\right|{\hat{\mathbf{y}}}\left\lbrace(\mathbf{y} - \boldsymbol{\theta})^{T}W(\mathbf{y} - \boldsymbol{\theta}) + \boldsymbol{\theta}^{T}P{\lambda}\boldsymbol{\theta}\right\rbrace = - 2 W(y - \hat{\mathbf{y}}) +2P_{\lambda} \hat{\mathbf{y}}.$$
It follows that $(W + P_{\lambda})\hat{\mathbf{y}} = W\mathbf{y}$, proving the above result. If $\lambda \neq 0$, $W + P_{\lambda}$ is invertible as long as $\mathbf{w}$ has $q$ non-zero elements in the one-dimensional case, and $\Omega$ has at least $q_x \times q_z$ non-zero elements spread across $q_x$ different rows and $q_z$ different columns in the two-dimensional case. These conditions are always met in real datasets.
How to use the package?
The WH package features a unique main function WH. Two arguments are
mandatory for this function:
-
The vector (or matrix in the two-dimension case)
dcorresponding to the number of observed events of interest by age (or by age and duration in the two-dimension case).dshould have named elements (or rows and columns) for the model results to be extrapolated. -
The vector (or matrix in the two-dimension case)
eccorresponding to the portfolio central exposure by age (or by age and duration in the two-dimension case) whose dimensions should match those ofd. The contribution of each individual to the portfolio central exposure corresponds to the time the individual was actually observed with corresponding age (and duration in the two-dimension case). It always ranges from 0 to 1 and is affected by individuals leaving the portfolio, no matter the cause, as well as censoring and truncating phenomena.
Additional arguments may be supplied, whose description is given in the documentation of the functions.
The package also embed two fictive agregated datasets to illustrate how to use it:
-
portfolio_mortalitycontains the agregated number of deaths and associated central exposure by age for an annuity portfolio. -
portfolio_LTCcontains the agregated number of deaths and associated central exposure by age and duration (in years) since the onset of LTC for the annuitant database of a long-term care portfolio.
# One-dimensional case
WH_1d_fit <- WH(portfolio_mort$d, portfolio_mort$ec)
Outer procedure completed in 14 iterations, smoothing parameters: 9327, final LAML: 32.1
# Two-dimensional case
WH_2d_fit <- WH(portfolio_LTC$d, portfolio_LTC$ec)
Outer procedure completed in 63 iterations, smoothing parameters: 1211.41,    1.09, final LAML: 276
Function WH outputs objects of class "WH_1d" and "WH_2d" to which
additional functions (including generic S3 methods) may be applied:
- The
printfunction provides a glimpse of the fitted results
WH_1d_fit
An object fitted using the WH function
Initial data contains 45 data points:
  Observation positions:  50  to  94
Smoothing parameter selected: 9327
Associated degrees of freedom: 6.8
WH_2d_fit
An object fitted using the WH function
Initial data contains 450 data points:
  First dimension:  70  to  99
  Second dimension:  0  to  14
Smoothing parameters selected: 1211.4    1.1
Associated degrees of freedom: 47
- The
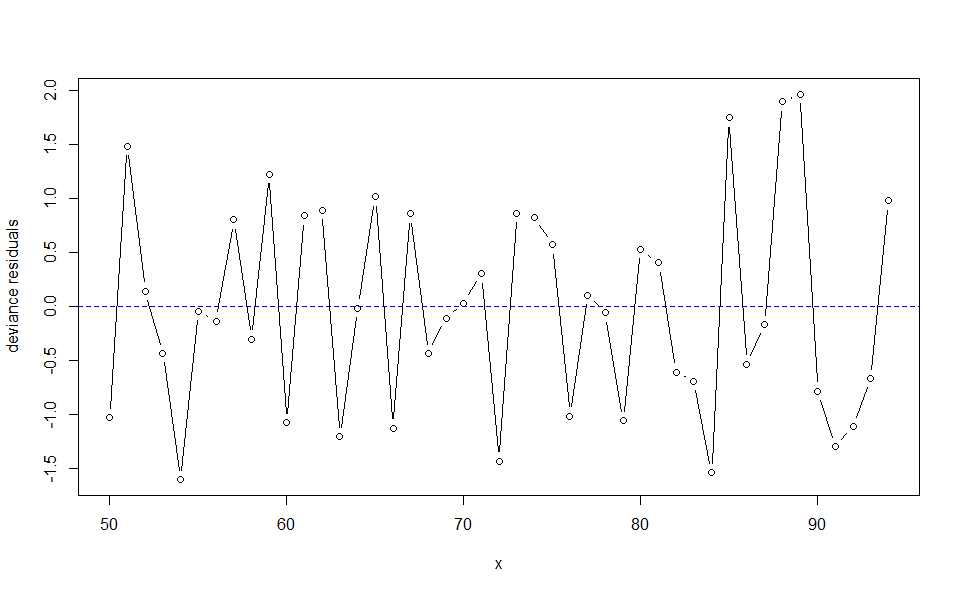
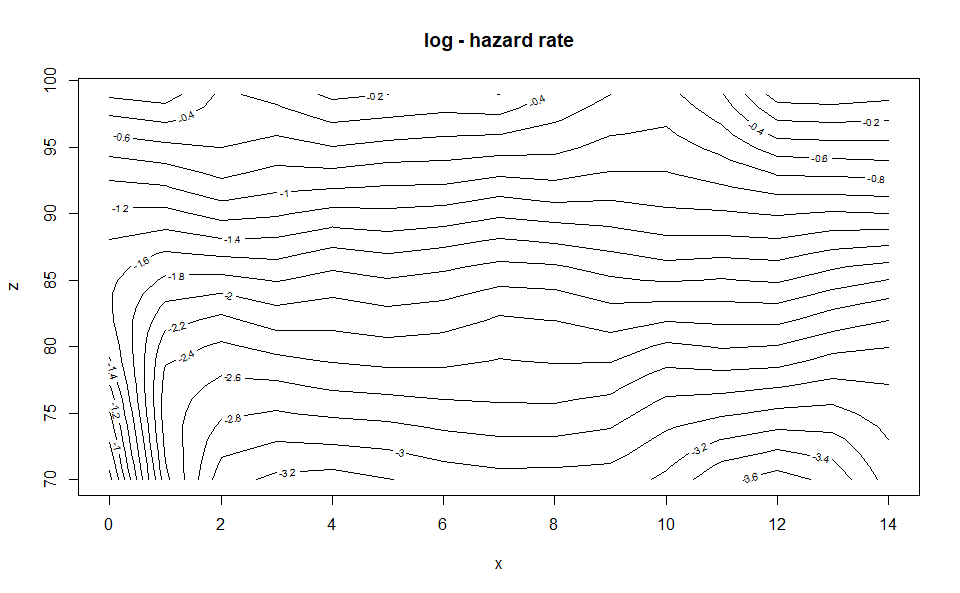
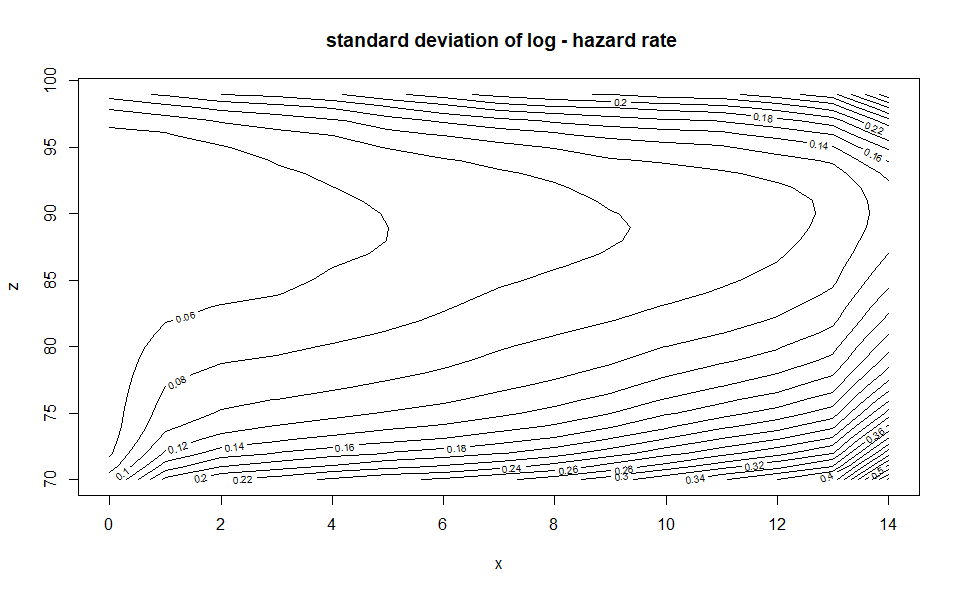
plotfunction generates rough plots of the model fit, the associated standard deviation, the model residuals or the associated degrees of freedom. See theplot.WH_1dandplot.WH_2dfunctions help for more details.
plot(WH_1d_fit)
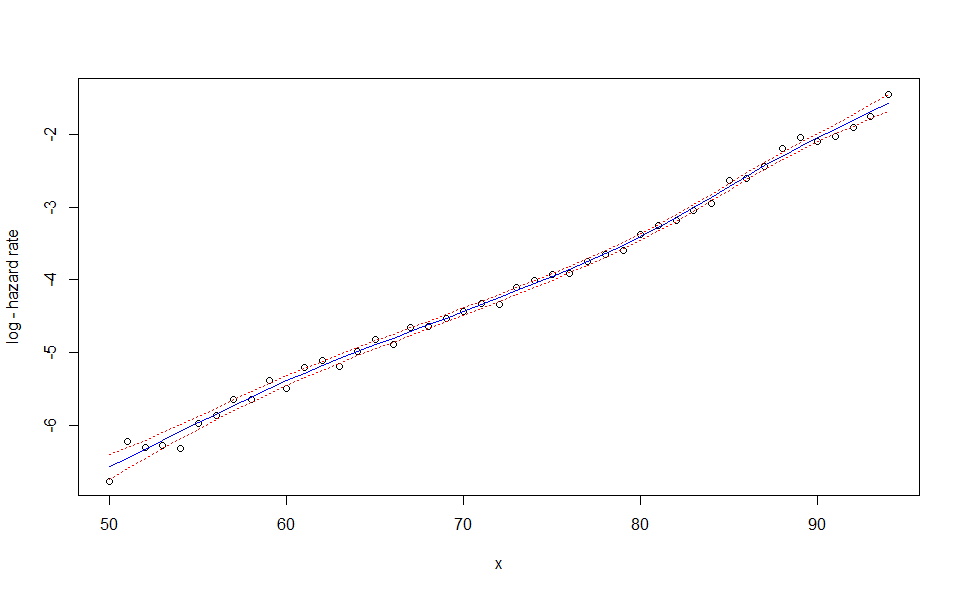
plot(WH_1d_fit, "res")
plot(WH_1d_fit, "edf")
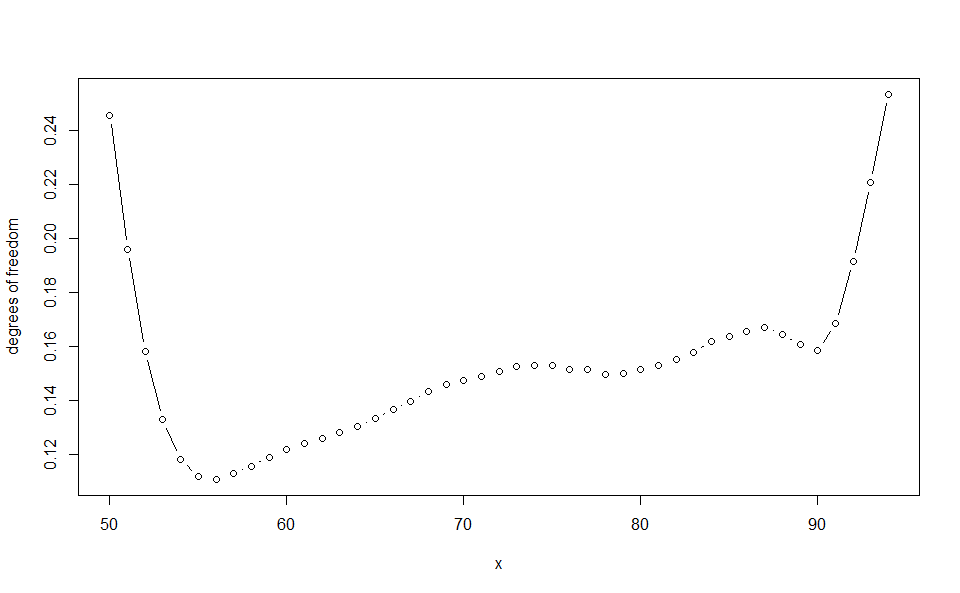
plot(WH_2d_fit)
plot(WH_2d_fit, "std_y_hat")
- The
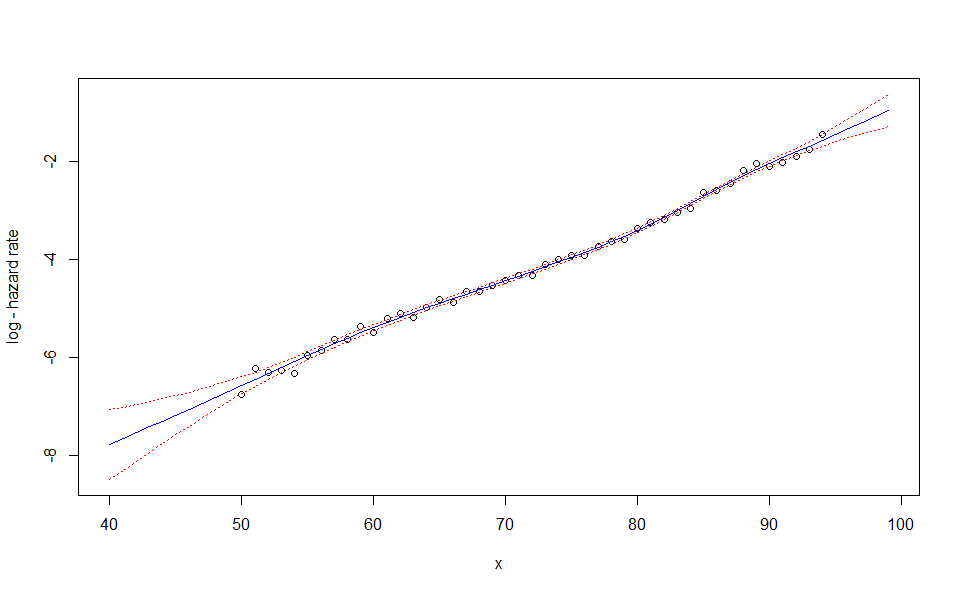
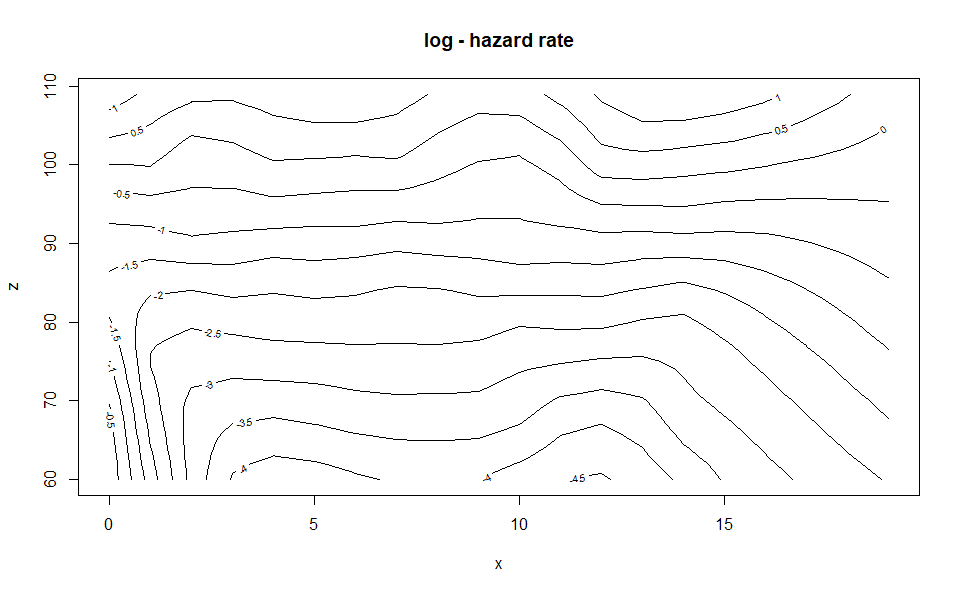
predictfunction generates an extrapolation of the model. It requires anewdataargument, a named list with one or two elements corresponding to the positions of the new observations. In the two-dimension case constraints are used so that the predicted values matches the fitted values for the initial observations (see Carballo, Durban, and Lee 2021 to understand why this is required).
WH_1d_fit |> predict(newdata = 40:99) |> plot()
WH_2d_fit |> predict(newdata = list(age = 60:109, duration = 0:19)) |> plot()
-
The
vcovmay be used to retrieve the variance-covariance matrix of the model if necessary. -
Finally the
output_to_dffunction converts an"WH_1d"or"WH_2d"object into adata.frame. Information about the fit is discarded in the process. This function may be useful to produce better visualizations from the data, for example using the ggplot2 package.
WH_1d_df <- WH_1d_fit |> output_to_df()
WH_2d_df <- WH_2d_fit |> output_to_df()
Further WH smoothing theory
See the upcoming paper available here
References
Bohlmann, Georg. 1899. “Ein Ausgleichungsproblem.” Nachrichten von Der Gesellschaft Der Wissenschaften Zu Göttingen, Mathematisch-Physikalische Klasse 1899: 260–71.
Carballo, Alba, Maria Durban, and Dae-Jin Lee. 2021. “Out-of-Sample Prediction in Multidimensional p-Spline Models.” Mathematics 9 (15): 1761.
Henderson, Robert. 1924. “A New Method of Graduation.” Transactions of the Actuarial Society of America 25: 29–40.
Knorr, Frank E. 1984. “Multidimensional Whittaker-Henderson Graduation.” Transactions of Society of Actuaries 36: 213–55.
Whittaker, Edmund Taylor. 1923. “On a New Method of Graduation.” Proceedings of the Edinburgh Mathematical Society 41: 63–75.